


The downturn within the know-how sector — dragged by inflation, greater rates of interest and geopolitical occasions — continues to persist, and some of the acutely impacted areas has been VC funding for startups, notably these exterior the U.S. In accordance with VC agency Atomico, corporations in Europe are on observe to boost simply $42 billion this yr — lower than half the $85 billion that startups within the area raised in 2022.
The figures come from Atomico’s large report on the state of European tech, which it publishes yearly.
It additionally discovered that startups within the area are elevating much less at every stage of funding from Seed by to Collection C (and past), with later stage and bigger corporations feeling a selected pinch: simply 7 “unicorns” (startups with a valuation of greater than $1 billion) are set to emerge this yr in Europe, in comparison with 48 in 2022 and 108 in 2021.

Picture Credit: Atomico (opens in a brand new window)
(opens in a brand new w
However there’s a silver lining within the story. Whereas total funding quantities are undoubtedly down on the final two years, Atomico’s idea is that 2021 and 2022 had been outliers by way of exercise — a consequence of decrease rates of interest, a surge of know-how utilization throughout the peak of the Covid-19 pandemic, and a pent-up quantity of funding amongst traders — elevating ever-larger from LPs eager to reap large returns from a buoyant business — that wanted to be deployed.
In different phrases, taking these two years out of the combo, it appears to be like like figures are following a slower, and maybe more healthy, progress curve upwards.
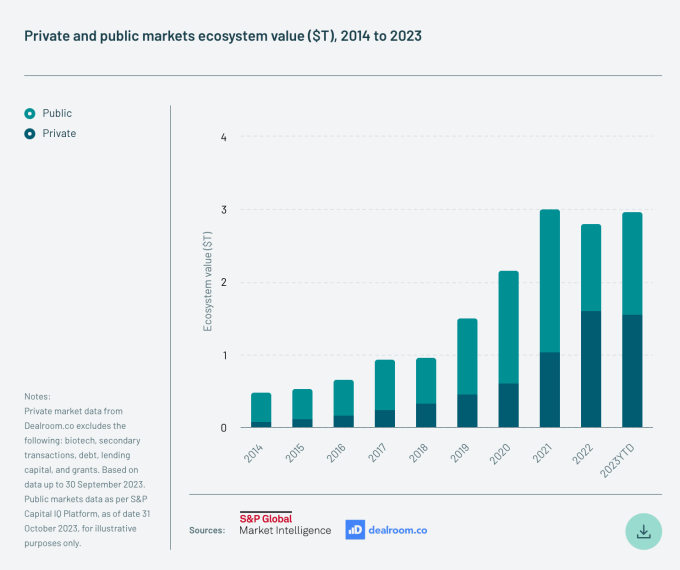
One other constructive signal is that the general complete worth of the European tech ecosystem — that’s, the mixed fairness worth of all private and non-private tech corporations in Europe — has returned to its 2021 report of $3 trillion after dropping $400 billion in worth in 2022. That’s because of a gentle stream of recent startups elevating cash offsetting down rounds, with the vast majority of fundraises made as flat rounds or up rounds.
Picture Credit: Atomico (opens in a brand new window)
“This rebound in ecosystem worth has additionally been supported by the continuous inflow of recent corporations beginning and elevating personal capital for the primary time, in addition to the truth that, regardless of a big enhance within the variety of down rounds, the overwhelming majority of follow-on capital deployed into the ecosystem has been by flat rounds or up rounds,” the authors of the report write.
Atomico bases its figures on surveys it runs with startups and traders, and enhances that with knowledge from third occasion sources like Dealroom, CrunchBase and others.
Among the different notable factors from the report:
“Crossover traders” have crossed out Europe. Atomico notes that so-called crossover traders — those that make investments each in personal and public tech corporations (Tiger International is one well-known instance) — have all however disappeared after driving a few of the greatest offers of earlier years. In 2021, there have been practically 100 mega-rounds the place these traders led or participated in Europe. 2022 began to see a slowdown of that tempo. This yr, spooked by the poor efficiency of each private and non-private tech corporations, these crossover gamers made simply 4 investments within the area.
Their absence has additionally impacted the general image for nine-figure rounds. Atomico notes that the primary 9 months of 2023 noticed simply 36 rounds of $100 million or extra, in comparison with tons of within the previous two years. Notably these rounds don’t observe the identical upward curve as another figures: there have been 55 $100+ rounds in 2020.

Picture Credit: Atomico (opens in a brand new window)
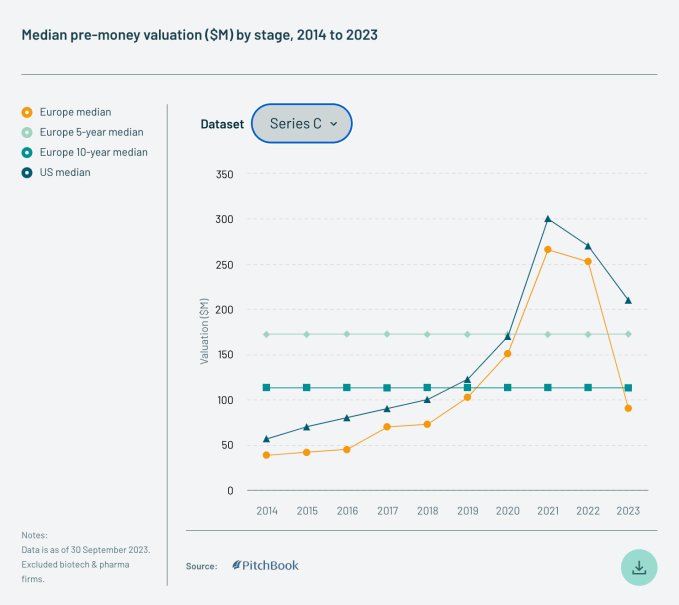
Planting the Seed. Startups at virtually each stage are elevating on common at down rounds, Atomico’s knowledge reveals. Typically, the later the stage, the starker the valuation drop. Right here is the image for Collection C rounds:
Picture Credit: Atomico (opens in a brand new window)
General, the median valuations for European startups stay significantly decrease than these of their U.S. counterparts — particularly between 30% and 60% decrease.
“This shift again towards longer-term averages in Europe mirrors what is occurring within the U.S.,” Atomico writes. In actual fact, between the U.S. and Europe, funding has dropped in practically each stage of investing between Seed and Collection C. The one exception is Seed stage within the U.S., which continued to rise, albeit at a slower price. (Median Seed rounds within the U.S. this yr, Atomico mentioned, was $11.5 million, whereas the European median determine was basically half that quantity: $5.7 million.)
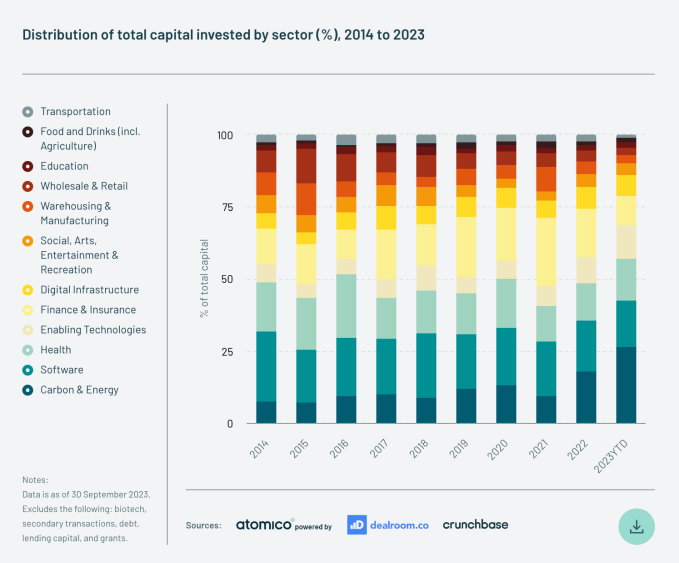
It’s not AI that’s dominating funding in Europe. Though the main target within the tech zeitgeist proper now definitely appears to be on synthetic intelligence, relating to what segments are driving precise funding monies proper now, for those who bounce on that bandwagon, you would possibly miss the true present. Atomico says that its numbers point out that local weather tech — and the broader space it’s in, Carbon and Vitality, accounted for a whopping 27% of all capital invested in European tech in 2023.
That’s greater than double what was invested on this space in 2023, and it’s even performing higher than a few of the different segments of tech which have historically be enormous within the area.
“Carbon & Vitality has soundly overtaken Finance & Insurance coverage and Software program as the only largest sector by capital raised,” the report authors observe. “This not solely represents a dramatic enhance within the scale of capital invested behind the inexperienced transition, but additionally a transparent slowdown in fintech funding volumes because the peak of the market.”
Picture Credit: Atomico (opens in a brand new window)

